BUSINESS
U.S. Crude Stocks Jump as WTI Ignores the Build
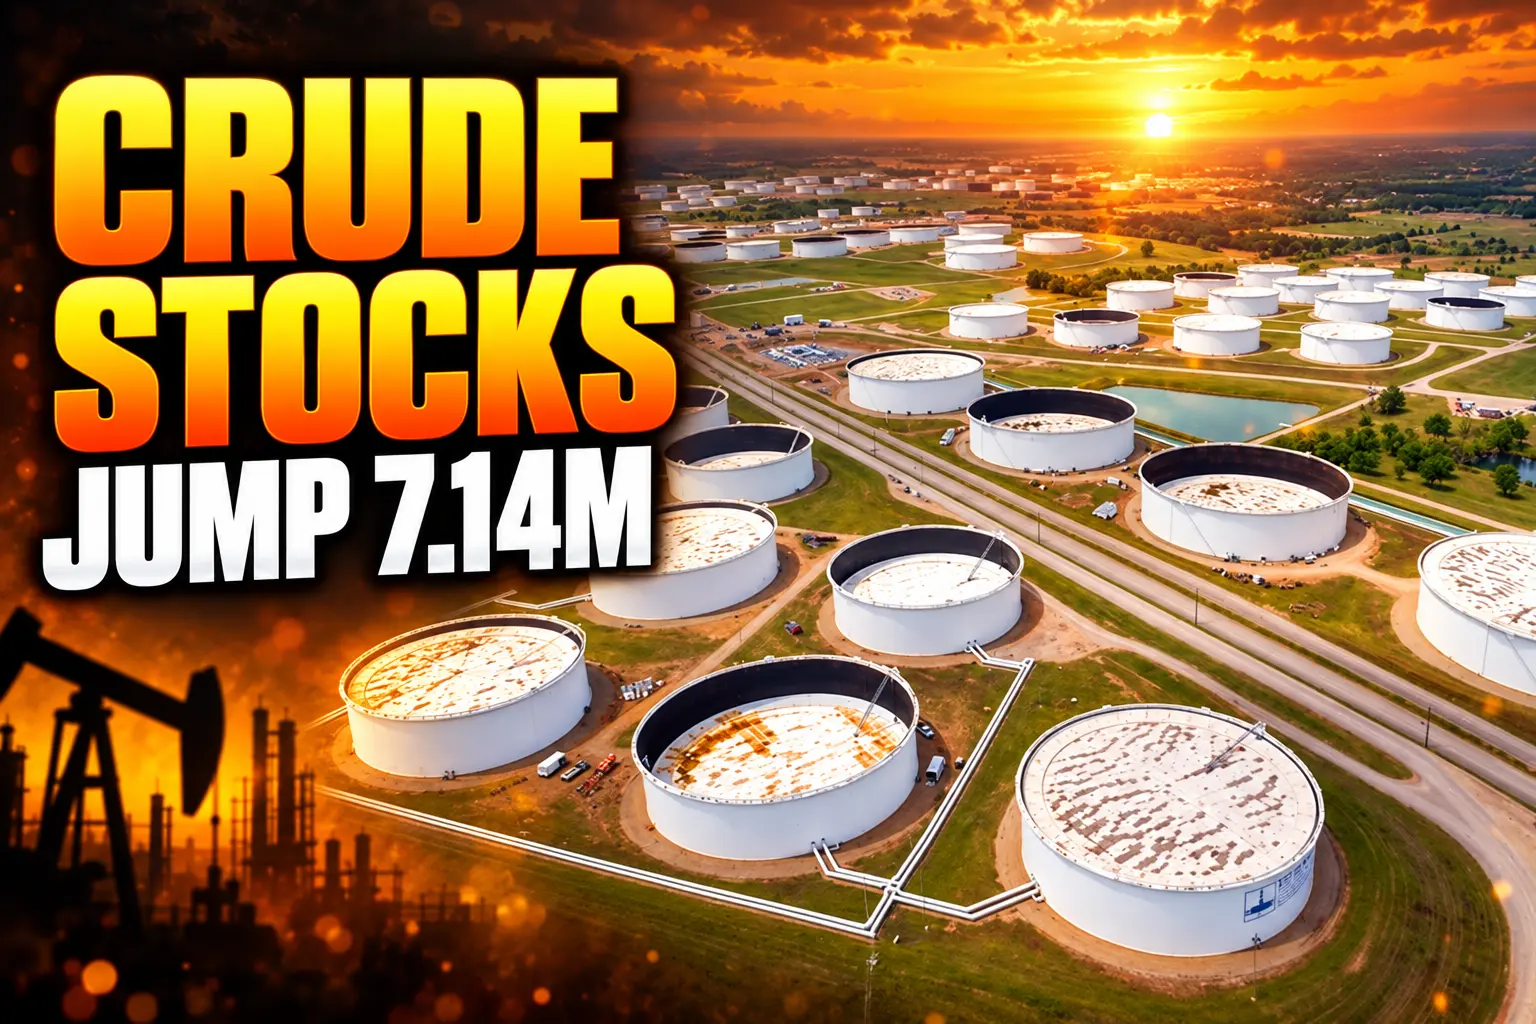
A 7.14 million barrel U.S. crude build left WTI near $107 because Cushing tanks and the SPR kept falling.

The American Petroleum Institute estimated U.S. crude stocks rose 7.14 million barrels in the week ending September 11. Traders had been looking for a 1.8 million barrel draw.
West Texas Intermediate still changed hands at $107.38 a barrel, up $3.83 on the session and about $11 from a week earlier, with Brent at $108.68. The extra oil showed up in the U.S. commercial system. It did not show up in the Oklahoma tanks that settle the WTI contract, and it did not refill the Strategic Petroleum Reserve.
A 7.14 Million Barrel Build Barely Budged WTI
API’s Tuesday estimate flipped a 300,000 barrel decline from the prior week into one of the fatter weekly builds of the year. The same tables showed gasoline stocks up 1.46 million barrels after a 1.9 million barrel drop, and distillate stocks up 1.61 million barrels on top of a 2 million barrel gain. Cushing, Oklahoma, the delivery hub for the WTI futures contract, still fell 246,000 barrels after a 300,000 barrel decline the week before.
That split is the whole print. A headline crude build this large is the sort of number that usually knocks several dollars off the front month. Prices held because the barrels landed in the commercial system as a whole, not in the one tank farm the futures contract actually delivers against, and because another 400,000 barrels left the SPR in the same week.
API WEEK ENDING SEPTEMBER 11
| Line | API change | Prior week | Street call |
|---|---|---|---|
| U.S. crude | +7.14 million bbl | -300,000 bbl | -1.8 million bbl |
| Gasoline | +1.46 million bbl | -1.9 million bbl | – |
| Distillate | +1.61 million bbl | +2 million bbl | – |
| Cushing crude | -246,000 bbl | -300,000 bbl | – |
| SPR | -400,000 bbl | – | – |
API’s crude number is an industry survey, not the government count. The Energy Information Administration is due to publish the official week ending September 11 figures on September 16. Until that print lands, the 7.14 million barrel figure is the number the market traded.
The reaction after the survey was the tell. WTI had just come off a session in which Saudi cargo cancellations and a shut East-West pipeline did the lifting. A build this far from the draw call should have given that bid something to fade. It did not.
Cushing Is Still the Tank That Prices the Contract
Cushing is a small Oklahoma town where pipelines from the Permian, the Bakken, the Rockies, and western Canada meet Midwest and Gulf Coast lines. NYMEX light sweet crude futures deliver there. When those tanks run low, the front of the WTI curve jumps even if tanks on the Gulf Coast or the East Coast are fuller.
The EIA’s week ending September 4 stock report put Cushing at 21.8 million barrels, down 0.7 million barrels from 22.5 million. That is 8.5 percent below the year-earlier 23.9 million barrels. Working storage at the hub was 78.4 million barrels of shell capacity in the March 2024 CME filing, with total shell space at 94.4 million. Traders have treated about 20 million barrels as the practical floor, the level where suction, tank bottoms, and crude quality start to get in the way of clean deliveries.
Cushing already spent stretches of June and July under that line. The EIA series showed 18.60 million barrels for the week ending July 24, after a mid-June print just below 19 million barrels, the lowest in more than a decade. The rebound to 21.8 million barrels by September 4 left only a thin cushion. API’s 246,000 barrel draw in the following week points back toward that floor, not away from it.
Commercial crude excluding the SPR told a calmer story. The EIA had those stocks at 424.1 million barrels for the week ending September 4, down 0.4 million barrels and matching the five-year average for the date. API data still show commercial crude excluding the SPR down just over 41 million barrels across the last 22 weeks, with total U.S. crude up nearly 10 million barrels for the year, a gap that only closes if you count SPR barrels moving into the commercial system.
Salt Caverns at 40 Percent of Capacity
The SPR held 285.4 million barrels in the week ending September 4, the EIA series shows, down 1.2 million barrels from 286.6 million. That is the lowest weekly level since November 5, 1982, and 40 percent of the Department of Energy’s 714 million barrels of authorized capacity. API estimated another 400,000 barrels left in the week ending September 11, taking the stockpile to about 285 million barrels.
The generally accepted operational band, below which the salt caverns can struggle to pump and process oil, is 250 million to 300 million barrels. The reserve is already inside that band. DOE still lists a maximum nominal drawdown rate of 4.4 million barrels a day and about 13 days from a presidential decision to oil reaching the U.S. market. Those rates assume pressure in the caverns. When the caverns are this empty, the effective rate drops to about 1 to 1.4 million barrels a day.
DOE paid an average of $29.70 a barrel for the oil now in the caverns. WTI at $107.38 is more than three times that acquisition cost, which is why a refill on the open market is a budget fight, not a plumbing one.
The 172 Million Barrel Hormuz Release
On March 11, President Trump authorized DOE to release 172 million barrels from the reserve over about 120 days, the U.S. share of a 400-million-barrel IEA stock release after the Strait of Hormuz closed. DOE is running the program as emergency exchanges: companies take SPR crude now and must return it later with extra barrels. The measured inventory still fell. The reserve held 415.4 million barrels in the week ending February 27 and 285.4 million in the week ending September 4, a drop of 130 million barrels.
That 2026 release stacked on top of the 180 million barrel emergency sale in 2022 after Russia invaded Ukraine. A late-2024 purchase program and canceled congressional sales had rebuilt the stockpile to 413.2 million barrels by the end of 2025. The Hormuz war took that refill back out. On August 30, President Trump said Venezuelan oil would be used to fill the reserve again. Weekly EIA figures through September 4 still show draws, not fills.
SPR CRUDE, 2026
- February 27, 2026: Holds 415.4 million barrels, near the 2025 refill.
- March 11, 2026: White House authorizes a 172 million barrel emergency exchange.
- July 24, 2026: Inventory prints 307.6 million barrels and keeps falling.
- August 28, 2026: Inventory prints 286.6 million barrels.
- September 4, 2026: Inventory prints 285.4 million barrels, a 1982 low.
- September 11, 2026: API estimates another 400,000 barrels leave, to about 285 million.
The four Gulf Coast sites (Bryan Mound and Big Hill in Texas, West Hackberry and Bayou Choctaw in Louisiana) still hold the oil in 61 salt caverns. DOE’s site sheet for August 20 showed 294.1 million barrels across those caverns, a different date and a different cut than the later EIA weekly total. Both cuts sit far below the 726.6 million barrel peak recorded on December 27, 2009.
A U.S. Stockpile Jump Does Not Replace Lost Gulf Barrels
The reason a 7.14 million barrel U.S. build did not cap a $107 tape is sitting outside U.S. tank gauges. Saudi Arabia’s East-West pipeline, the Red Sea bypass built to move crude around the Strait of Hormuz to Yanbu, was taken offline after a drone attack on September 11. Saudi refiners in Europe were then told some late-September cargoes were canceled. Hormuz itself has been a war zone since late February, when fighting with Iran shut the waterway that normally handles a large share of seaborne crude.
Paper Brent at $108.68 is not the same market as the wet barrel. Commodity analyst Giovanni Staunovo wrote on September 15 that dated Brent back at $130 a barrel while the front futures contract traded at $107, a gap that only opens when prompt physical oil is scarce and later-dated paper still prices some recovery.
Dated Brent (spot prices) is back at USD 130/bbl, while the Brent front futures contract trades at USD 107/bbl
Giovanni Staunovo, commodity analyst, on X
Ukrainian drone strikes have also cut into Russian diesel. Three of Russia’s six largest diesel plants were shut or running at about a quarter of nameplate, with Kirishi offline and Volgograd and NORSI near 25 percent, after attacks on plants that together make about half of Russia’s diesel. The International Energy Agency has already cut its outlook for Russian processing to about 4 million barrels a day, 30 percent below pre-invasion levels, and marked Russian crude supply at 8.7 million barrels a day for 2026.
U.S. commercial tanks can fill on a week like this and still leave the global prompt market short. The 7.14 million barrels API counted are real in the survey. They are not Yanbu loadings, and they are not Russian gasoil that never left the Baltic.
Distillate Tanks 13% Below the Seasonal Norm
Products are the other reason a crude build did not read as slack. Heading into the API week, the EIA had gasoline inventories 5 percent below the five-year average after a 1.3 million barrel increase to 206.9 million barrels. Distillate inventories rose 2.1 million barrels in that official week and were still 13 percent below the five-year average.
THE TANKS THAT ARE STILL SHORT
- SPR crude: 285.4 million barrels as of September 4, 40 percent of authorized space, a 1982 low.
- Cushing crude: 21.8 million barrels as of September 4, with API pointing to another 246,000 barrel draw.
- Gasoline: 206.9 million barrels, 5 percent below the five-year average heading into the API week.
- Distillate: 13 percent below the five-year average even after back-to-back weekly builds.
API’s product builds (1.46 million barrels of gasoline, 1.61 million barrels of distillate) chip at those deficits. They do not close them in a week. Distillate is the fuel that has been tightest since Russian plants started going offline and Middle East barrels stopped moving on schedule, and two fat weeks of builds still leave the tanks well below the seasonal line.
WHAT THE 7.14 MILLION BARRELS DO NOT FIX
- The delivery hub: Cushing is the WTI contract, and it kept falling.
- The emergency reserve: the SPR is inside its 250 million to 300 million barrel operating band.
- The prompt cargo: dated Brent near $130 is the price a refiner pays for oil that exists this month, not oil in a U.S. tank next quarter.
Total U.S. crude including the SPR was 709.4 million barrels on September 4, down 1.6 million barrels on the week, because the 0.4 million barrel commercial dip plus the 1.2 million barrel SPR draw added up even before API’s later commercial build. A commercial build financed by SPR oil is a transfer, not new supply.
Domestic Wells Cannot Fill a Closed Strait
U.S. crude production for the week ending September 4 rose to 13.947 million barrels a day from 13.862 million, up 452,000 barrels a day from a year earlier. The EIA also applied a 65,000 barrel a day re-benchmark that week, about 0.47 percent of the estimated total, after its monthly survey ran hotter than the weekly model. American fields are pumping. They are not a substitute for a closed strait and a shut Saudi bypass, and they do not put oil into Cushing by themselves.
WHAT WE KNOW
- API crude: +7.14 million barrels for the week ending September 11, versus a 1.8 million barrel draw call.
- Official SPR: 285.4 million barrels on September 4, lowest since November 5, 1982.
- Official Cushing: 21.8 million barrels on September 4, with API showing another draw.
- Price snapshot: WTI $107.38 and Brent $108.68 as the API number hit the tape.
WHAT IS UNCONFIRMED
- EIA crude: the government count for the week ending September 11 is due September 16 and can revise API by several million barrels.
- East-West restart: no public date for when the Yanbu line returns, or how many canceled September cargoes stay canceled.
- SPR refill: Venezuelan barrels have been promised; weekly figures through September 4 still show withdrawals.
If the EIA confirms anything close to a 7 million barrel crude build and WTI still holds above $105, the market will have said the same thing twice: U.S. commercial tanks can take oil and the contract can still bid up the barrel that can actually be loaded. Cushing drew again in the API week. Another 400,000 barrels left the SPR. Those are the tanks that still set the price.
Disclaimer: This article is news reporting and analysis of weekly petroleum inventory figures and oil prices, and it is for information only. It is not investment advice, trading advice, or a recommendation to buy or sell crude oil, refined fuels, futures, shares, or any other instrument. Readers who are considering energy-market decisions should consult a licensed financial adviser or commodities broker who can review their own position, time horizon, and risk limits. Inventory totals, SPR volumes, and prices are taken from the API survey, EIA weekly series, and DOE figures cited above and can change with the next official print.

Morocco’s Next World Cup Government Starts 101 Seats Short

TSA CT Scanners Catch Oversized Carry-On Bags at Security

False AI Intel Nearly Put US Crews on a Chinese Ship

Anthropic Will Pay Accenture to Grade Its Own Models

U.S. Crude Stocks Jump as WTI Ignores the Build

How to Get Pre Boarding on Southwest – Skip the Line with These Tricks

Tim Cook’s $4.6 Trillion Apple Still Runs on One Phone

Dunes Air Sues Nora Fatehi Over Its Luxury Jet

OpenAI Posts a Navier-Stokes Proof Clay Has Not Touched

China’s Supreme People’s Court Gives AI Apps Safe Harbor
-
 TRAVEL3 years ago
How to Get Pre Boarding on Southwest – Skip the Line with These Tricks
-
 BUSINESS1 month ago
Tim Cook’s $4.6 Trillion Apple Still Runs on One Phone
-
 ENTERTAINMENT3 weeks ago
Dunes Air Sues Nora Fatehi Over Its Luxury Jet
-
 NEWS3 weeks ago
OpenAI Posts a Navier-Stokes Proof Clay Has Not Touched
-

 LIFESTYLE3 years ago
How Long Does It Take for Armpit Hair to Grow? The Stages of Hair Growth and How to Shave It
-
 NEWS3 weeks ago
China’s Supreme People’s Court Gives AI Apps Safe Harbor
-

 NEWS3 weeks ago
Australia Treats Cloud Software Payments as Taxable Royalties
-

 BUSINESS3 weeks ago
Samsung India Cuts TV Jobs as Its Chip Unit Booms