BUSINESS
The PB Fintech Slide Prices in a Distribution Overhaul
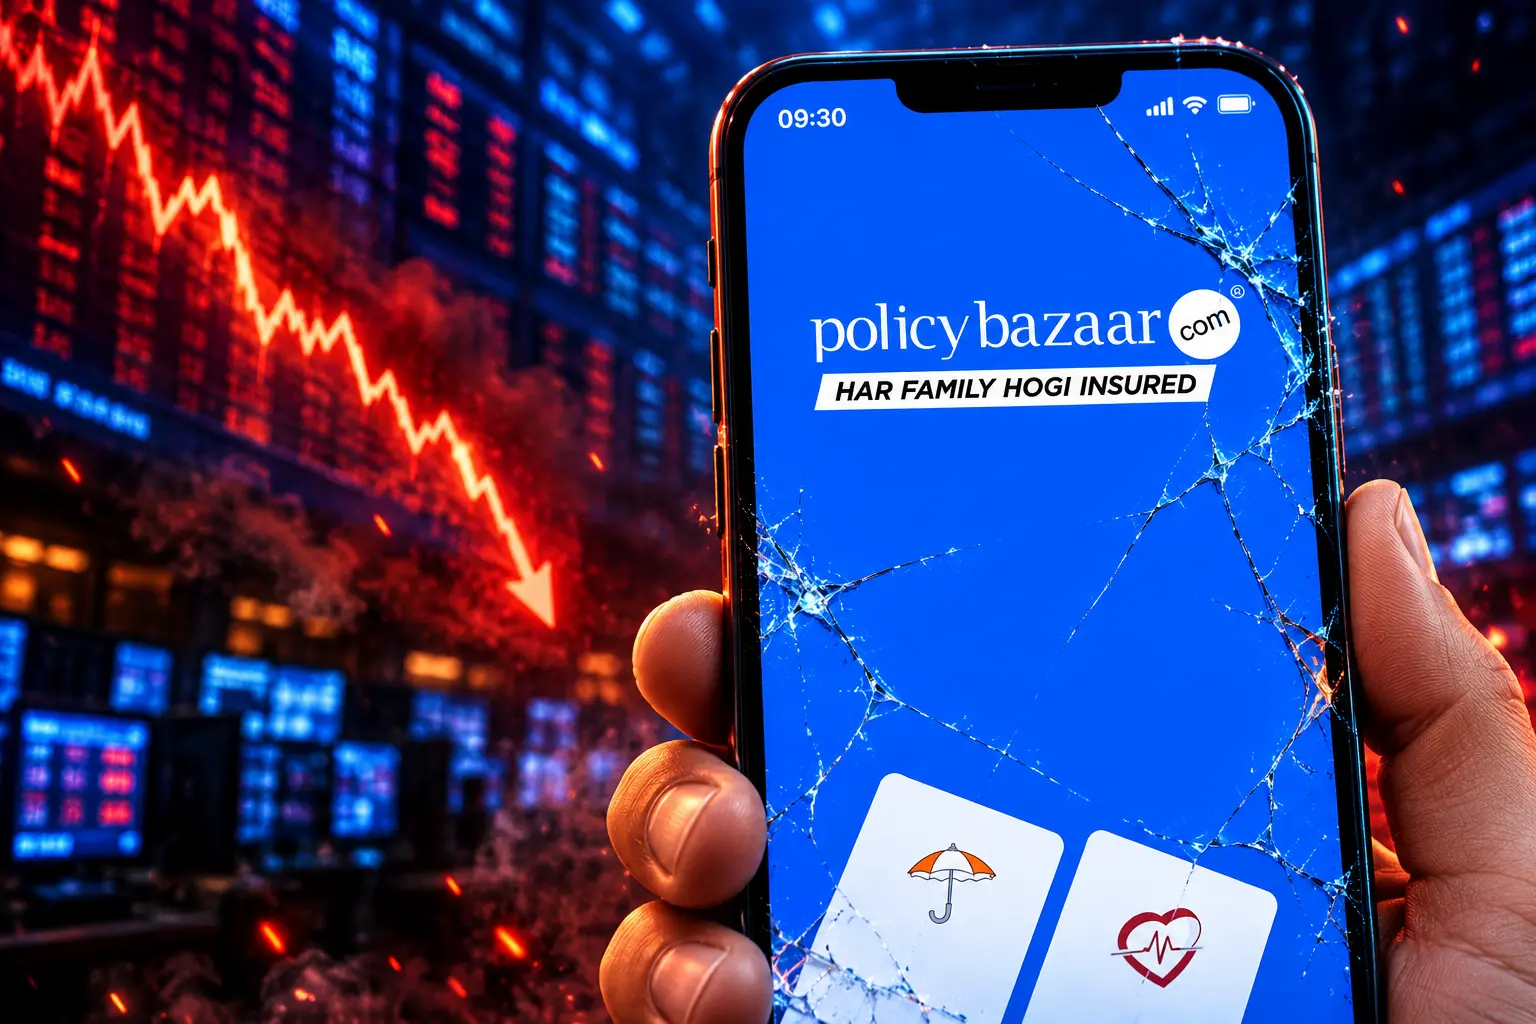
PB Fintech fell further on Friday after a 36 percent crash, as IRDAI’s draft would pay brokers and banks less than tied agents to sell insurance.

PB Fintech shares were last at Rs 1,154 on Friday, September 25, down 4.4 percent, after jumping as much as 4 percent at the open. Thursday’s 36 percent crash had already taken the Policybazaar parent to a then 52-week low of Rs 1,207.20, wiping out more than Rs 31,000 crore ($3.27 billion) of market value in one session.
The selling is the listed market’s way of pricing a draft from the Insurance Regulatory and Development Authority of India that would pay banks, brokers and web aggregators less than tied agents for the same policy. Policybazaar is simply the cleanest listed share for that channel. HSBC and Motilal Oswal now both target Rs 1,150, almost exactly where the stock was last.
IRDAI Caps Payouts for Brokers and Banks
On 23 September the regulator issued a two-part public consultation paper titled Recalibrating Economics of Insurance Distribution. It would bring back product-wise commission caps that IRDAI removed in 2023, count gifts, trips and other extras toward those caps, and fold today’s many intermediary licences into Insurance Distribution Entities, Insurance Distribution Persons, and insurer-backed Market Infrastructure Institutions.
Open-architecture sellers (banks, brokers, aggregators) would face lower first-year caps than agents tied to one insurer. IRDAI’s stated reason is that multi-insurer platforms make it too easy to push whichever company pays more. Comments are due by 25 October. If adopted, the new economics are sketched to start in FY28.
THE PROPOSED COMMISSION CAPS
| Product | Distribution entity | Tied agent | Typical payout now |
|---|---|---|---|
| Health, first year | 15% | 20% | Over 30% |
| Health, renewal or port | 5% | 10% | About 20% |
| Life, first year (10+ year PPT) | 20% | 25% | Often over 40% |
| Pure term, first year | 25% | 30% | About 51% average |
| Motor third-party, new vehicle | Nil | 2.5% | 25% to 50% |
| Credit life, first year | 2% to 2.5% | – | About 45% |
Macquarie put the observed average first-year commission on regular-premium pure term at 51 percent for distribution entities, against a proposed 25 percent cap. Bernstein put health payouts at more than 30 percent on new sales and about 20 percent on renewals, against 15 percent and 5 percent in the draft. Motor own-damage on a new vehicle would be capped at 5 percent for a distribution entity and 10 percent for an agent. Compulsory third-party cover on a new car would pay the entity nothing.
The same paper would tighten insurers’ own Expense of Management limits over five years, with FY28 as year one. Life insurers would go to 15 percent of gross direct premium income in two years and 12.5 percent in five, with a 10 percent endpoint for firms already below the line. General insurers would move toward 20 percent of domestic GDPI in five years, after 25 percent in two. Insurers that overshoot could be blocked from new products, dividends, or the channel that overspent.
Why Policybazaar Became the Listed Proxy
Almost 90 percent of PB Fintech’s operating revenue is insurance commission: Rs 6,089 crore of Rs 6,794 crore in FY26. That is why a draft written for the whole sales chain hit this ticker first, and hardest. The company’s FY26 earnings presentation still reads like a compounding story, which is what the market had been paying for until Wednesday night.
PB FINTECH IN FY26
- Operating revenue: Rs 6,794 crore, up 37 percent from Rs 4,977 crore.
- Profit after tax: Rs 670 crore, up 90 percent from Rs 352 crore, or 115 percent excluding a Rs 41 crore exceptional item in FY25.
- Insurance premium: Rs 29,934 crore, up 42 percent; core online premium Rs 20,390 crore, up 39 percent.
- Core online margin: Adjusted EBITDA of Rs 841 crore, a 21 percent margin, with protection (health and term) more than 70 percent of core online insurance revenue.
The full-year results filing also shows Rs 935 crore of renewal revenue, the trail book investors treat as the high-quality annuity. The draft caps that trail too. Health renewal and porting commissions for a distribution entity would be 5 percent. Motilal Oswal estimated the package could cut FY28 core online insurance revenue by around 30 percent and, with no cost or other revenue offsets, earnings estimates by 46 percent.
Jefferies said a 10 percent cut in new-business commission rates alone could take 10 to 12 percent off earnings for distributors such as PB Fintech and Turtlemint. The actual draft is steeper than that 10 percent thought experiment: Jefferies put the hit at at least half on new health and term commissions and about a third on motor own-damage. HSBC downgraded the stock to Hold, cut its target to Rs 1,150 from Rs 2,100, and lowered FY28 earnings per share estimates by 56 percent and FY29 by 17 percent.
Banks and NBFCs Share the Same Blast Radius
The share that can actually be sold in size is Policybazaar. The rule that would change the most money sits in bank branches and NBFC loan desks. One life-insurer executive said the non-agency channel is about half of business today, of which about 65 to 70 percent is banks. First-year commissions on loan-bundled life cover are proposed at 2 to 2.5 percent for distribution entities, against effective payouts of about 45 percent now. Compulsory bundling of insurance with a loan would be banned.
Macquarie’s FY26 cut of bank insurance fees shows why Axis Bank and HDFC Bank moved more than State Bank of India. Axis took insurance fee income to 2.4 percent of revenue and 12.5 percent of profit before tax. HDFC Bank was at 1.9 percent of revenue and 7.3 percent of PBT. Kotak Mahindra Bank was 1.6 percent and 5.8 percent. SBI was 0.5 percent and 2.6 percent. ICICI Bank was 0.2 percent and 0.6 percent. IIFL estimated most NBFCs could take a 4 to 8 percent hit if they offset about half through costs, fees or lending yields.
THURSDAY’S HIT LIST
- PB Fintech: Down 36 percent to Rs 1,207.20, the steepest drop since listing.
- Turtlemint: Down 20 percent to Rs 109.10, hitting its lower circuit.
- Axis Bank and IDFC First Bank: Down 4.6 percent and 4.7 percent; IndusInd Bank down 4.2 percent; HDFC Bank down 1.1 percent.
- HDFC Life and ICICI Life: Down 6.7 percent and 4.4 percent. Agency-heavy, lower-cost books such as LIC and SBI Life were treated as more insulated.
A cheaper policy does not fall out of a lower commission by itself. Insurers can keep the spread, or sales teams can simply work fewer files, especially away from big cities. The draft tries to patch that with extra commission for policies sold in towns of up to 50,000 people, rural areas, and cities of up to 10 lakh. Whether that extra is enough is a later argument. Thursday priced the cut, not the patch.
The 2023 Cap Removal That Inflated Payouts
IRDAI spent 2023 taking product-wise commission caps off the table and putting an overall Expense of Management ceiling in their place, in a 30 to 35 percent band of premium. Boards were meant to set their own commission policy inside that envelope. The new paper says that board sign-off has often been a formality, and that distributor pay then ran far ahead of the business it bought.
FROM DE-CAPPING TO THIS DRAFT
- 2023: Product-wise commission caps are removed; insurers operate under an EoM cap of about 30 to 35 percent of premium.
- FY23 to FY25: In a sample covering about 92 percent of life premium through corporate agents, new-business premium rises 28 percent while total distributor pay, including rewards, rises 125 percent. In general insurance placed through brokers, premium rises about 37 percent while commission including rewards rises about 173 percent.
- 23 September 2026: IRDAI publishes the two-part consultation, proposing effort-based caps, a five-year EoM glide, and a ban on forced loan-insurance bundling.
- 24 September 2026: PB Fintech falls 36 percent. Management holds an analyst call the same afternoon.
- 25 September 2026: The stock is last at Rs 1,154, and prints a fresh 52-week low of Rs 1,115, with market value below Rs 53,500 crore. PB Fintech is down about 36 percent in 2026; the Nifty 50 is down 11.8 percent.
- 25 October 2026: Comment window closes. Proposed go-live, if the draft holds, is FY28.
Thomas Devasia, a former IRDAI member for non-life, called bringing back product-level caps regressive, because the EoM framework was the more flexible way to police cost. Swami Saran Sharma, founder of Helios Global Solutions, said distributors often keep no more than about 5 percent as net commission after their own costs, even when headline payouts run above 30 percent. Those two views can both be true: a 15 percent cap can still starve a platform whose cost base was built for a 30 percent take, while an insurer’s total expense line looks like progress on a slide.
Dahiya Would Rather Build an Insurer
Co-founder and group CEO Yashish Dahiya told analysts on 24 September that the paper was “quite extreme.” He put the general-insurance revenue hit at between one-third and 40 percent of today’s level, a different quantity from Motilal’s 30 percent cut to FY28 core online insurance revenue, and said life’s existing book was not the main wound. He ruled out mass layoffs, said the firm hired about 6,000 people in the first half, and added it might have hired closer to 2,000 had the draft been known. FY27 would be unaffected. FY28, if the rules land, would be “challenges and discovery.”
In terms of general insurance, it is between one-third to 40% of what we have today. So that’s a very serious impact on revenue.
Yashish Dahiya, co-founder and group CEO, Thursday analyst call
He said digital marketing, brand spend, sales and customer support would be reviewed, and hiring slowed rather than reversed. Then he went further. Remaining only a distributor gets harder to justify, he said, if the draft takes away the idea that quality of business is paid for. He has not wanted to underwrite policies. The proposal, he said, has almost forced the company to look at manufacturing, and at reinsurance, hospital and garage networks, and claims technology as other ways to get paid. International plans stay. Growth will be calibrated to “the new reality.”
That is the second turn of the same screw. If open-architecture pay is capped below the cost of running a comparison site, the site either shrinks or tries to become an insurer. Entry capital for a new distribution entity would fall to Rs 10 lakh with perpetual registration, which points the other way: more, smaller sellers, not fewer. Both can happen at once. Large platforms retrench. Tiny IDEs multiply. The comparison layer in the middle is what Thursday sold.
Rs 1,150 Is Now the Street Target
HSBC’s new Hold rating and Motilal Oswal’s Neutral both land at Rs 1,150. Friday’s last price of Rs 1,154 is four rupees above that number. The 52-week high was Rs 1,964.20. Motilal said the stock could stay heavy until the final regulations are out. That is not a riddle. The tape has already moved the price onto the post-draft target, and left the next move to Hyderabad’s comment file.
Friday’s session still had air in it. The share rallied as much as 4 percent after Thursday’s washout, then reversed, and traded as low as Rs 1,115. With the Nifty barely changed, this was not a market tape. It was one name still digesting a 160-odd-page rewrite that has not been notified, and a pair of notes that cut FY28 earnings in half in one case and by 46 percent in the other.
October 25 Closes the Comment Window
None of the caps is in force. IRDAI asked whether customers should pay sellers a fee they can see, instead of an insurer-paid commission they cannot. It also wants the premium to move from the buyer’s own account, UPI or card straight to the insurer, with an OTP check before issue, and it wants vehicle dealers to tell buyers they can buy cover on Bima Sugam. Those plumbing changes matter as much as the percentages, because they attack the last places where a seller can sit between the customer and the company.
WHAT WE KNOW
- Status: The text is a consultation, not a notified regulation, and the comment deadline is 25 October 2026.
- Clock: The expense glide and commission grid are written to start in FY28 if they survive the consultation in this form.
- Channel bias: Tied agents would be allowed higher first-year caps than banks, brokers and aggregators on the same product.
WHAT IS UNCONFIRMED
- Final grid: Whether the 15 percent health cap, the nil motor-TP payout, or the 2 to 2.5 percent credit-life cap survive lobbying by banks and distributors.
- Premiums: Whether any of the saved commission shows up as a cheaper policy, a richer life bonus, or a fatter insurer margin.
- PB’s next form: Whether Policybazaar files to underwrite, or only slows hiring and marketing until the final gazette.
The 36 percent session was the listed proxy doing its job. Banks, NBFCs, motor dealers and a long tail of brokers sit on the same draft and do not have a single ticker that moves 36 percent when Hyderabad publishes. Comments close on 25 October. If this grid holds, the first full year under it would be FY28, and Friday’s last price is already sitting on the new street target of Rs 1,150.
Disclaimer: This article is news reporting and analysis of PB Fintech’s share-price move and of IRDAI’s consultation paper. It is informational only and is not investment advice, a research report, or a recommendation to buy, sell or hold any share, bond, insurance policy or other product. Readers should consult a SEBI-registered investment adviser or other qualified financial professional before making any investment decision, and should not treat brokerage target prices or draft regulatory caps as forecasts. Figures, ratings and the status of the IRDAI proposals reflect the sources available on 25 September 2026 and can change as comments are filed and as the stock trades.

A CubeSat Will Age Whisky That Never Comes Home

A Charity Quote Cost Shia LaBeouf the FKA twigs NDA

Looker Turned a Model’s Body Into Ad Inventory

Infinity Ward Bets a Paid DMZ Will Stick This Time

Disney Sidesteps a Kimmel Renewal as Failla Cites Losses

How to Get Pre Boarding on Southwest – Skip the Line with These Tricks

False AI Intel Nearly Put US Crews on a Chinese Ship

Tim Cook’s $4.6 Trillion Apple Still Runs on One Phone

OpenAI Posts a Navier-Stokes Proof Clay Has Not Touched

Dunes Air Sues Nora Fatehi Over Its Luxury Jet
-
 TRAVEL3 years ago
How to Get Pre Boarding on Southwest – Skip the Line with These Tricks
-
 NEWS1 month ago
False AI Intel Nearly Put US Crews on a Chinese Ship
-
 BUSINESS2 months ago
Tim Cook’s $4.6 Trillion Apple Still Runs on One Phone
-
 NEWS2 months ago
OpenAI Posts a Navier-Stokes Proof Clay Has Not Touched
-
 ENTERTAINMENT2 months ago
Dunes Air Sues Nora Fatehi Over Its Luxury Jet
-
 LIFESTYLE3 years ago
How Often Do You Have to Change a Monkey’s Diaper? The Truth About Pet Monkeys
-
 NEWS2 months ago
Australia Treats Cloud Software Payments as Taxable Royalties
-

 LIFESTYLE3 years ago
How Long Does It Take for Armpit Hair to Grow? The Stages of Hair Growth and How to Shave It